Prestige Padi EMI Calculator

Featured Image of Prestige Padi EMI Calculator


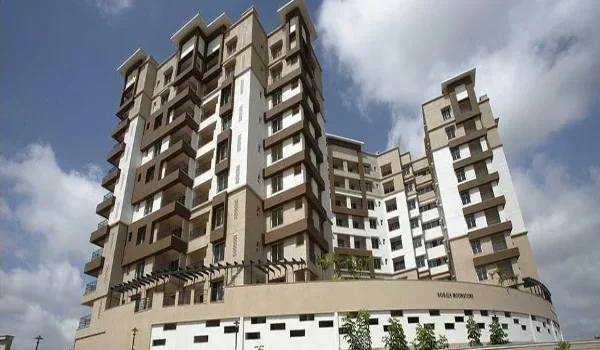
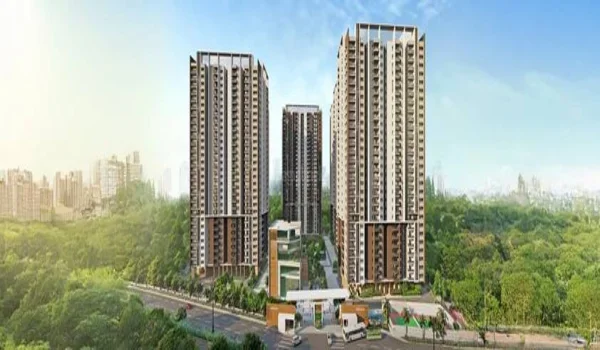
The Prestige Padi EMI calculator is a financial assessment tool that determines the Equated Monthly Instalment across 2,200 apartment units spanning 18 to 20 towers in this 16-acre high-rise development on CTH Road, Chennai. It models monthly loan liabilities against the project’s specific configuration prices, which start at ₹74.3 Lakhs for a 550 sq. ft. 1 BHK and scale to ₹3.24 Crores for a 2,400 sq. ft. 4 BHK luxury residence.

By processing the sanctioned 80% loan amount alongside annual interest rates ranging from 8.35% to 9.50% and tenures between 10 and 30 years, it provides buyers with clear amortisation schedules before booking. This calculation enables prospective buyers to verify whether their monthly debt service fits comfortably within the recommended 40% to 50% household income threshold.

What Is the Prestige Padi EMI Calculator?


The Prestige Padi EMI calculator is an online tool that works out your exact monthly loan instalment for a flat in this 16-acre township. It breaks down your total purchase cost into a simple, month-by-month payment schedule spread across 10 to 30 years.

Banks like SBI, HDFC Bank, ICICI Bank, and Axis Bank use this same standard formula to set your monthly dues. The tool takes away your 20% down payment from the flat cost, applies your bank interest rate, and shows your real monthly bill in seconds:

EMI = [P x R x (1+R)^N] / [(1+R)^N - 1]

  • P (Principal): The actual home loan amount you take from the bank after paying your 20% down payment.
  • R (Monthly Interest): Your bank's yearly interest rate divided by 12 months, then divided by 100.
  • N (Tenure): The total number of months you choose to repay your home loan.

Prestige Padi Unit Prices and Monthly Loan EMI Estimates


Prestige Padi offers flats from 550 sq. ft. up to 2,400 sq. ft., and each flat size requires a different loan amount. The table below shows what you pay each month if you pay a 20% down payment and take an 80% home loan at an 8.50% yearly interest rate for 20 years:

Unit Configuration Size Range (sq. ft.) Starting Flat Price 20% Down Payment 80% Bank Loan Monthly EMI (8.5% for 20 Yrs)
1 BHK 550 – 650 ₹74,30,000 ₹14,86,000 ₹59,44,000 ₹51,570
2 BHK 900 – 1,150 ₹1,22,00,000 ₹24,40,000 ₹97,60,000 ₹84,670
2.5 BHK 1,200 – 1,350 ₹1,62,00,000 ₹32,40,000 ₹1,29,60,000 ₹1,12,440
3 BHK 1,350 – 1,800 ₹1,82,00,000 ₹36,40,000 ₹1,45,60,000 ₹1,26,320
4 BHK 2,000 – 2,400 ₹2,70,00,000 ₹54,00,000 ₹2,16,00,000 ₹1,87,390
4 BHK Luxury Up to 2,400 ₹3,24,00,000 ₹64,80,000 ₹2,59,20,000 ₹2,24,870

How Loan Tenure Affects Prestige Padi EMI and Total Interest


The number of years you choose for your loan changes both your monthly payment and your total extra interest. The table below shows what happens when you repay a ₹97.60 Lakh loan for a 2 BHK flat at an 8.50% interest rate across different loan lengths:

Loan Tenure Monthly EMI Total Interest You Pay Total Money You Pay (Loan + Interest)
10 Years (120 Months) ₹1,21,000 ₹47,60,000 ₹1,45,20,000
15 Years (180 Months) ₹96,110 ₹75,40,000 ₹1,73,00,000
20 Years (240 Months) ₹84,670 ₹1,05,61,000 ₹2,03,21,000
25 Years (300 Months) ₹78,570 ₹1,38,11,000 ₹2,35,71,000
30 Years (360 Months) ₹75,050 ₹1,72,58,000 ₹2,70,18,000
  • A 15-year loan costs ₹11,440 more each month than a 20-year loan, but it saves you ₹30,21,000 in pure bank interest.
  • A 30-year loan lowers your monthly instalment by ₹9,620, but it forces you to pay an extra ₹66,97,000 in interest to the bank.
  • Choosing a tenure between 15 and 20 years offers the best mix of easy monthly payments and lower overall interest.

Pre-EMI vs. Full EMI Calculation for Prestige Padi Under Construction


Buying an under-construction home at Prestige Padi lets you pick between two bank payment options before you move in.

  • Pre-EMI Option: You pay only the basic interest on the money the bank releases to the builder as construction moves floor by floor. Your monthly payment stays very small during construction, but none of this money pays off your actual loan balance.
  • Full EMI Option: You start paying your full monthly instalment right away, covering both interest and principal balance. This helps you clear a big chunk of your debt before taking possession, and you avoid sudden payment shocks later on.

Primary Factors Determining Prestige Padi EMI Amounts


Four main points decide whether your monthly flat payment goes up or down.

  • Down Payment Size: Paying 25% or 30% upfront instead of the basic 20% brings down your loan amount and cuts thousands off your monthly bill.
  • Your CIBIL Score: A score of 750 or higher gets you the lowest bank interest rates near 8.35% to 8.50%, while lower scores push your rates and EMIs higher.
  • Floor Choice and View: Flats on higher floors (levels 14 to 16) or units facing open gardens cost more per square foot, which slightly increases your loan and monthly payment.
  • Adding a Co-Applicant: Adding a working spouse to your loan application increases your total eligible borrowing limit and often helps you secure lower interest rates.
FAQs


1. What is the minimum down payment needed to book an apartment at Prestige Padi?

You pay 10% of the flat cost at booking and another 10% when signing your sale agreement, making a 20% down payment in total. Your bank funds the remaining 80% in stages as the towers get built.

2. Does the Prestige Padi EMI calculator include registration and stamp duty?

No, the calculator only computes your main home loan and bank interest. You must budget an extra 7% for Tamil Nadu stamp duty and 2% for state registration charges from your own savings.

3. What monthly take-home salary is required to qualify for a 2 BHK loan?

Banks check that your monthly home loan payment does not eat up more than half your monthly income. For a 2 BHK with an EMI of ₹84,670, your household should earn at least ₹1,70,000 to ₹1,90,000 in clear take-home pay each month.

4. How do changes in the RBI repo rate affect floating-rate EMIs?

When the Reserve Bank of India changes the repo rate, commercial banks adjust their home loan rates right away. This change either alters your monthly EMI amount or shortens/lengthens the total number of months left on your loan.

5. Can Prestige Padi buyers make prepayments to lower their monthly EMI?

Yes, RBI rules state that banks cannot charge extra fees when you make part-payments on floating-rate home loans. Any extra money you pay goes straight toward reducing your principal balance, which cuts your monthly bill or ends your loan years earlier.

Enquiry
Enquire Now